Before you download anything, ask the uncomfortable question: what actually broke in your last budget? For most people it is not math. It is that the tool they picked did not match how they live — a spreadsheet when they wanted automation, or an app that auto-sorted everything when they wanted hands-on control.
So which budgeting app is best? There is no single answer. Best means what serves you — Merriam-Webster defines the word as "most productive of good: offering or producing the greatest advantage, utility, or satisfaction" — and that varies with your habits, your income pattern, and how much control you want. What follows is a comparison by workflow, not a ranking.
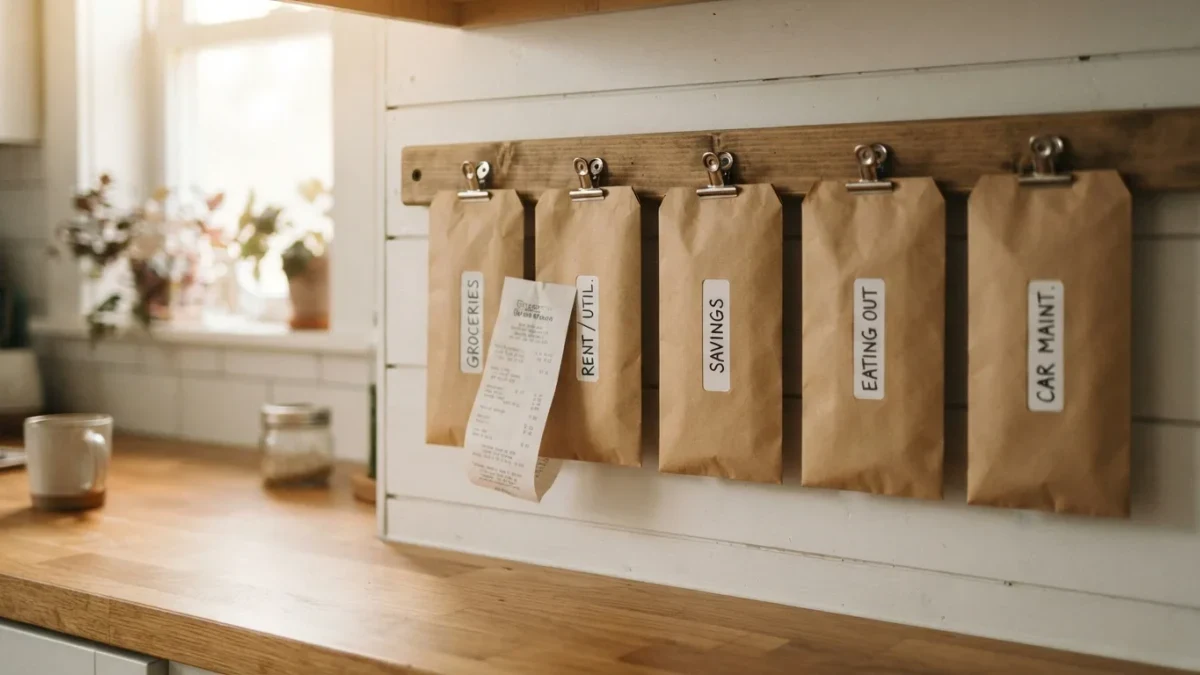
One term to define up front: envelope budgeting is the habit of assigning every dollar a job before you spend it — historically with cash in physical envelopes, now with digital "envelopes" inside an app. If that idea appeals, your app choice is already half made.
What are the main types of budgeting apps?
It helps to group budgeting apps into three broad families. Knowing which family you belong to matters more than comparing feature lists.
- Envelope-style apps. You assign each dollar to a category before the month starts. When a category runs out, the app shows it immediately. These suit people who want to make spending decisions in advance, not review them afterward.
- Auto-tracking apps. You link your bank accounts and the app sorts transactions into categories for you. You review, you do not plan. These suit people who want awareness with minimum effort.
- Spreadsheet-linked tools. Some apps sit on top of a spreadsheet, or export to one. You keep full control of every formula and category. This suits people who already trust their own system and want a tool that does not fight it.
Whatever tier or trial an app offers, terms change often — check the current pricing page before you commit to anything.
Which app fits an envelope budgeting workflow?
If you want to give every dollar a job, choose an app built around planning rather than reviewing. The test is simple: can you assign money to a category before you spend it, and does the app stop you — or at least warn you — when a category is empty?
Envelope-style tools demand more of you, especially in the first month. You will spend an evening setting up categories and assigning your income. The payoff is that mid-month decisions become easy: the envelope balance, not your bank balance, tells you whether you can spend.
If this is the workflow you want, our guide to how envelope budgeting works with digital tools walks through the mechanics step by step. And if you are starting from zero, how to start a budget in your first 90 days covers the setup sequence that works before any app is involved.
Which app fits an auto-tracking workflow?
If planning every dollar in advance sounds exhausting, an auto-tracking app is the honest answer. You connect your accounts, the app categorizes your spending, and you check a dashboard once a week. The limitation is real, though: automatic categories can be wrong, so expect to spend a few minutes correcting them each week.
This family works best for people with steady income who mostly want to know where the money went — not to control where it goes next. If your income changes month to month, auto-tracking alone will not solve your problem; you still need a plan for the lean months. How to budget when your income changes every month covers that planning layer.
Which app fits a spreadsheet-first workflow?
If you already run your money in a spreadsheet, the best app may be the one that adds the least. Look for tools that import transactions cleanly, export without locking your data, and let you keep your own categories. Avoid anything that hides your numbers behind its own dashboard.
The trade-off is manual work. Spreadsheets do not remind you, categorize for you, or alert you when a category is overspent — unless you build those features yourself. Many people accept that trade because they want their data in a format they own and can carry anywhere.
What this means for your choice: a practical checklist
Here is a short test you can run before paying anything. Try each step with the app's free tier.
- Match the workflow, not the feature list. Envelope planner, auto-tracker, or spreadsheet layer — pick the family first.
- Check the connection. If you want bank syncing, confirm the app supports your bank before you subscribe. Connection quality can vary over time.
- Test the category edit. Add a transaction, recategorize it, split it. If that takes more than a few taps, you will stop doing it.
- Read the pricing page yourself. Subscription terms, free tiers, and trial lengths change. Verify them on the company's own site, on the day you decide.
- Give it one full pay cycle. A budgeting tool that feels awkward in week one may click by week four — or confirm it is wrong for you.
Whichever app you choose, the categories you set up matter more than the software. If you are unsure where to start, how the 50/30/20 budget works, with real numbers gives you a simple starting structure, and what sinking funds are — and why they rescue December explains the category most apps handle badly.
The limits of any budgeting app
An app cannot fix a spending plan that does not exist. It also cannot tell you what a typical month should look like — for that, what the average US household spends each month, and how to use it in your budget gives you benchmarks to compare against your own numbers.
Two honest limits worth naming. First, connected apps require granting access to your financial accounts — read the app's security and data-sharing terms before linking accounts, and decide what you are comfortable with. Second, no app guarantees an outcome. The tool that works is the one you will actually open, and a plain spreadsheet you update weekly beats a feature-rich app you abandon in a month.
That is the whole comparison in one line: match the tool to the workflow you already have, verify the terms yourself, and let one full pay cycle decide. Our full budgeting section has more on each method mentioned here.