Before you build anything, ask the uncomfortable question: do you actually know where last month's paycheck went? If the honest answer is no, that is the problem a budget fixes — and budgeting for beginners works best when you start with one pay cycle, not a perfect yearly plan. A budget is simply a plan for how you'll spend and save your money each month, built on your take-home pay.
Here's the encouraging part: a first draft takes under an hour. The Penny Hoarder notes that most people can rough out a starter budget in a single sitting, using just a few months of bank statements. This guide walks you through one full cycle — the numbers, the method, and the mistakes that trip up almost everyone on the first try.
What does a budget actually do?
A budget gives every dollar a job before the month starts. You take the money that hits your bank account after taxes — your take-home pay, not your gross salary — and you decide ahead of time where it goes: bills, savings, debt, and yes, some guilt-free spending.
That last part matters. A budget is not a diet. It tells you what you can spend on the things you enjoy, because everything else is already covered. The Penny Hoarder's own State of Savings survey found that 48% of Americans simply save whatever is left after bills rather than planning it — which is exactly the leak a budget plugs.
There's a stress benefit too. The same publication's 2026 Financial Anxiety Barometer reported that 43% of Americans worry about their personal finances several times a week. Knowing your numbers doesn't change the money. It changes how aware of it you are, and that awareness is what makes the 2 a.m. worry fade.
How do you set up your first budget in five steps?
The five steps are: calculate take-home income, list your expenses, set goals, pick a method, and track and adjust. Here's each one in order.
- Calculate your monthly take-home pay. Use the amount that actually lands in your account. Include side gigs, tips, and benefits — but use a conservative average for anything variable. If your income swings, average the last three to six months and plan on the lower end. If that's your situation, our guide to budgeting when your income changes every month goes deeper.
- List every expense from the last three months. Pull your bank and card statements and split each expense into fixed (rent, insurance, subscriptions) and variable (groceries, gas, dining out). Three months is long enough to catch quarterly bills and short enough to stay manageable.
- Set one or two goals. A starter emergency fund or a specific debt is enough. Vague goals die; named ones get funded.
- Pick a method. Two beginner-friendly options are covered below.
- Track and adjust weekly. A budget you never check is just a wish. Ten minutes each week is enough.
For the first 90 days of the habit itself, see our walkthrough on how to start a budget in your first 90 days.
What does one full pay cycle look like with real numbers?
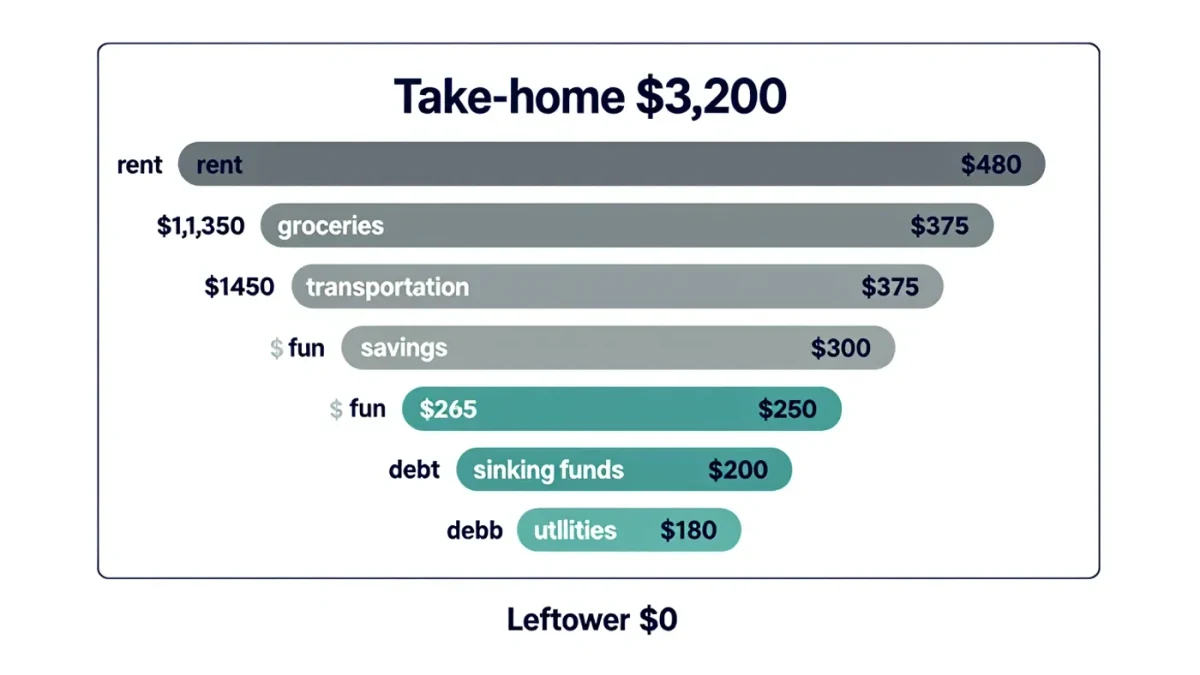
Here's a worked example with every assumption stated. Say you bring home $3,200 a month, paid twice a month. Your three months of statements show these fixed costs: rent $1,100, utilities $180, phone $60, car insurance $120, and groceries budgeted at $550 on purpose — more on that below. Transportation runs $300. That's $2,310 committed to essentials.
That leaves $890. Assign it: $300 to savings, $200 to a credit card payment, $290 to spending you enjoy, and $100 as a miscellaneous line for the things no one predicts. Income minus assignments equals zero. Nothing is unaccounted for.
Notice the deliberate overestimate on groceries. Ramsey recommends rounding up your estimates at first — if you think you spend $500 on groceries, budget $550 — because beginners almost always underestimate variable categories, and an early blown budget is what makes people quit. The $100 miscellaneous line does the same job for everything else. If you live close to the edge, our piece on budgeting paycheck to paycheck covers tighter versions of this same structure.
Which budgeting method should a beginner use?
The two most common starting points are zero-based budgeting and the 50/30/20 rule. Both work; they suit different personalities.
| Criterion | Zero-based budgeting | 50/30/20 rule |
|---|---|---|
| Core idea | Every dollar is assigned until income minus expenses equals zero | Rough split: needs, wants, savings and debt |
| Setup time | Longer at first; a monthly plan can be built in under 30 minutes with an app, per Ramsey | Fast — three buckets |
| Best for | People who want full control and to see every dollar | People who want structure without line items |
| Trade-off | Needs a monthly check-in | Percentages may not fit a high-rent area |
Zero-based budgeting means assigning every dollar of income to a category — give, save, or spend — before the month begins, so nothing slips through. Our explainer on what zero-based budgeting is and whether to try it shows the full mechanics. If you'd rather start looser, how the 50/30/20 budget works with real numbers gives you the three-bucket version. And if you'd rather use software than a spreadsheet, our comparison of budgeting apps lays out the options on price and features.
Which expenses come first when money is short?
Cover the essentials before anything else. Ramsey calls these the Four Walls: food, utilities, shelter, and transportation. They keep your household stable, and every other category waits until they're funded.
One more habit worth building early: look at next month's calendar before it starts. Birthdays, car maintenance, and holidays don't surprise you if you plan for them. That's what sinking funds are for — our guide to what sinking funds are and why they rescue December explains how to save small amounts ahead of known expenses.
What this means for your first month
Our analysis of the common failure points is simple: beginners quit because their first budget was a fantasy, not because budgeting is hard. The fixes are all in the setup. Use take-home pay, not gross. Round up your variable estimates. Keep a miscellaneous line. Check in weekly, and adjust the plan each month rather than judging yourself against a frozen one. This connects to our earlier piece, What the average US household spends each month, and how to use it in your budget.
Expect the first cycle to be rough. The goal of month one is not a perfect budget — it's an honest one. By month two or three, your estimates start matching reality, and the plan starts feeling like control instead of restriction. That's the whole game.