Before you spend a bonus or tax refund, ask the uncomfortable question: if this money disappears into your regular spending, what will you have to show for it in three months? Most windfalls die quietly that way. The fix is to treat the money as a decision, not a mood.
A windfall is any lump sum outside your normal paycheck — a work bonus, a tax refund, a cash gift. The safest default is to slow down: park the money, keep your monthly budget untouched, and decide its job deliberately. To adjust, in the plain sense Merriam-Webster defines it, is to bring the parts of something to a more effective relative position — which is exactly what a windfall lets you do with a budget that has been under strain.
What this means in practice: your regular budget keeps running on your regular income. The bonus gets its own plan, decided once, in writing, before the money starts moving. This guide walks through that plan in five steps, plus the mistakes that most often undo it.
Why does a windfall wreck a budget that was working?
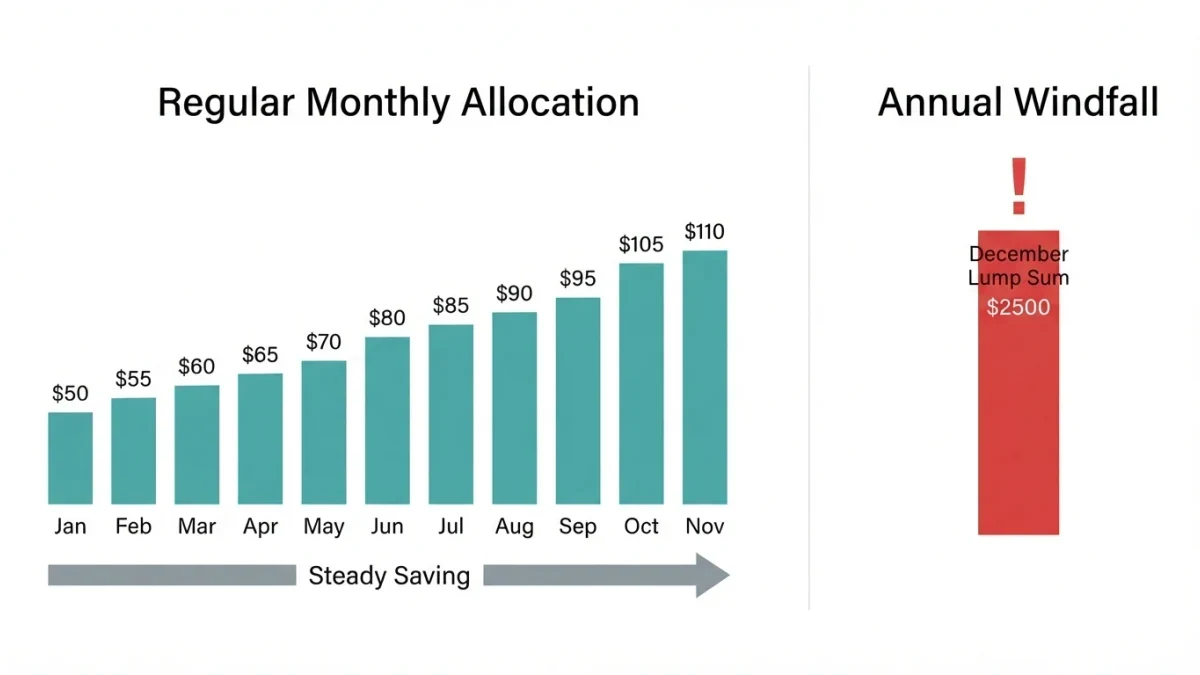
Because it looks like a raise, and it isn't. A raise changes every future month. A bonus changes one month and then stops. If you fold it into your everyday spending — a few nicer dinners, a cart upgrade, a subscription or two — the extra month ends but the higher habits stay, and next month's budget comes up short.
The second risk is mental, not mathematical. Windfall money feels free, so it skips the questions your paycheck money faces. Nothing in your budget is free; every dollar has a job. The goal is to give the bonus the same discipline your regular income already has, without the guilt trip if some of it goes to enjoyment.
What should you do in the first 48 hours?
Do nothing with the money itself, and do three small things around it. This is the pause that keeps a windfall from becoming a story you tell about a stranger.
- Leave it parked. Keep it in the account where it landed. Don't move it toward anything yet.
- Write down the claims on it. Upcoming bills, a thin emergency cushion, high-cost debt, a goal you've been circling for months. Just list them.
- Set a decision date. Give yourself a few days. A bonus that sits still for a week loses nothing; a bonus spent in a rush often does.
If your income already swings month to month, the same pause applies — and how to budget when your income changes every month covers the baseline system this windfall plan sits on top of.
What order should the money go in?
There is no single right split, but there is a defensible order of operations. Work down the list and stop where your situation says stop. This is general information, not financial advice — the right answer depends on your debts, your job stability, and what your budget already covers.
- Urgent needs first. If a bill is about to go unpaid or a necessary repair is pending, that's the job. A windfall that keeps the lights on is never wasted.
- A starter cushion. If you have little or no emergency cash, even a partial fill of that gap changes how the next bad month feels. For the mechanics, see how to budget when you live paycheck to paycheck.
- Expensive debt. Debt with a high interest rate is a guaranteed cost; paying it down is a guaranteed saving. Check the rate on your own statement rather than assuming.
- Sinking funds and lumpy expenses. The annual costs that break budgets — holidays, car maintenance, insurance renewals — are exactly what sinking funds are for. A windfall can pre-fund several at once.
- Longer-term goals. Only after the above. If investing is on the list, know that markets can lose value, and a lump sum you may need soon doesn't belong in them.
It is fine to end the list with a deliberate slice for enjoyment — say a modest percentage you choose in advance. A budget you resent is a budget you abandon. The point of the order is that fun comes after the cushion, not instead of it.
How do you fold the decision into your regular budget?
Adjust the plan, not the machine. Your monthly budget — whether it's the 50/30/20 split or zero-based budgeting — keeps running on your normal paycheck. The windfall is a one-time line item with its own allocation, recorded the same way you'd record any other planned expense.
Three things worth writing down when you do:
- The split itself. Percentages are easier to commit to than dollar amounts, and they scale to whatever actually arrives.
- The tax reality. A bonus is usually taxed up front, sometimes at a flat supplemental rate, so the check is smaller than the headline number. Your refund, by contrast, is money you already overpaid — yours to allocate in full.
- What you're saying no to. Naming the un-chosen option makes the decision feel like a choice rather than a loss.
Our analysis of where windfall plans fail: almost never at the allocation step. They fail at the boundary step — the moment the bonus money and the paycheck money start sharing a category. Keep them separate until every dollar of the bonus has a named job.
What if the windfall is bigger than a month's income?
Then the pause matters more, not less. Large sums justify a slower decision and, for anything beyond paying down debt or building cash savings, a conversation with a fee-only financial professional who can see your whole picture. Two cautions apply at any size:
- Don't lend what you can't gift. Money to family and friends should be decided as a gift you can afford to lose, not a loan you expect back.
- Beware the pitched product. A sudden lump sum makes you a target for anyone selling urgency. Anyone pressuring you to decide today is telling you something about themselves.
If part of the plan involves investing, the basics live in our investing section — and the honest framing is that investing is for money with a long horizon, and losses are possible.
The takeaway
A windfall is a chance to adjust the parts of your budget into a more effective position — urgent needs, then cushion, then expensive debt, then the lumpy annual costs, then goals, with a small deliberate slice for enjoying it. Decide once, in writing, within a few days of the money arriving. Your monthly plan doesn't change; it just gets one good month of help. That's a small win worth protecting.
Sources: merriam-webster.com · dictionary.cambridge.org · thefreedictionary.com