A payday loan is a small, short-term advance against your next paycheck. You walk out with cash today, and the lender collects the full amount — the loan plus a fee — from your bank account on your next payday, usually a week or two later. The core thing to understand is that the sticker fee looks small but the annualized cost is high, because the fee is charged on a very short loan.
That structure is the whole story. A flat fee on money you hold for two weeks is not the same as a flat fee on money you hold for a year. When you stretch that same fee out over a full year of borrowing, the rate climbs far above what a credit card or a personal loan would charge. This piece walks through how the fee works, how the renewal trap operates, and what lower-cost options usually sit nearby. For related coverage, see The Fed cut rates in December 2025 — here is what it means for your money.
How does a payday loan actually work?
The mechanics are simple, and the simplicity is part of the pitch. You show the lender proof of income — a pay stub or benefits letter — and a checking account. The lender writes you a loan for a portion of your next paycheck. In many states, you either leave a post-dated check or sign an authorization letting the lender pull the money from your account electronically on the due date.
When the due date arrives, the lender collects the full amount at once. There is no monthly payment and no amortization — the paying-down of a loan a piece at a time — the way there is with a car loan or a credit card. It is one lump sum, one date. If the money is not there, the bank may charge you an overdraft or returned-payment fee on top of what the lender charges, which is where costs start stacking. We covered a connected angle in What FDIC deposit insurance covers, and how to protect more than $250,000 at one bank.
Loan sizes are capped by state law, and the caps vary a lot from state to state. Some states cap the amount, some cap the fee, and a handful effectively ban the product altogether. That means two borrowers doing the identical thing in neighboring states can face very different legal costs. Check your own state's rules before you assume anything about what a lender near you may charge.
Why does the fee translate into such a high annual rate?
Here is the arithmetic that matters, using a purely illustrative example — not a quoted rate from any lender. Suppose a lender charges 15 dollars per 100 dollars borrowed, and you borrow 300 dollars for two weeks. The fee is 45 dollars. That feels manageable against a paycheck.
Now annualize it. You are paying 45 dollars to rent 300 dollars for one twenty-sixth of a year. Multiply 45 by 26 and you get 1,170 dollars a year for the same 300 dollars — an annualized rate in the hundreds of percent. No number of adjectives says that as clearly as the multiplication does. The point is not that every lender charges that exact fee; it is that any flat fee compressed into a two-week loan produces a very large annual rate, which is why regulators and consumer agencies keep returning to this product.
This is also the question worth asking about any short-term credit: where does the fee actually sit, and who eats it? With a payday loan, the fee sits entirely on the borrower, upfront, and it is due whether or not the loan helped you get through the month.
What happens if you cannot pay on the due date?
This is where short-term lending gets expensive for a lot of people. Many lenders offer a renewal or rollover: instead of paying the loan off, you pay a new fee and the due date moves out. Each renewal charges a fresh fee on the same borrowed money. A borrower who rolls a loan over several times can pay more in fees than the original amount borrowed — a pattern consumer regulators have documented repeatedly.
Some states restrict rollovers or limit how many times a loan can be renewed, precisely because of this. Federal rules have also targeted the repeated-attempt problem: when a lender tries to pull money from your account multiple times, each failed attempt can trigger another bank fee. If you see a due date coming that you cannot meet, contact the lender before the date rather than after. Some will work out an extended payment plan, and state rules in some places require them to offer one. Asking costs nothing.
What are the lower-cost alternatives to compare?
Before taking a payday loan, it is worth pricing the alternatives, because several exist and most cost less. None of these is a guarantee — approval depends on your situation — but they are the standard comparison set.
- Credit union loans. Many credit unions offer small-dollar installment loans with far lower rates than payday products, and federal credit unions operate under rate caps set by their regulator. Membership rules are looser than most people expect; some credit unions let you join based on where you live or work.
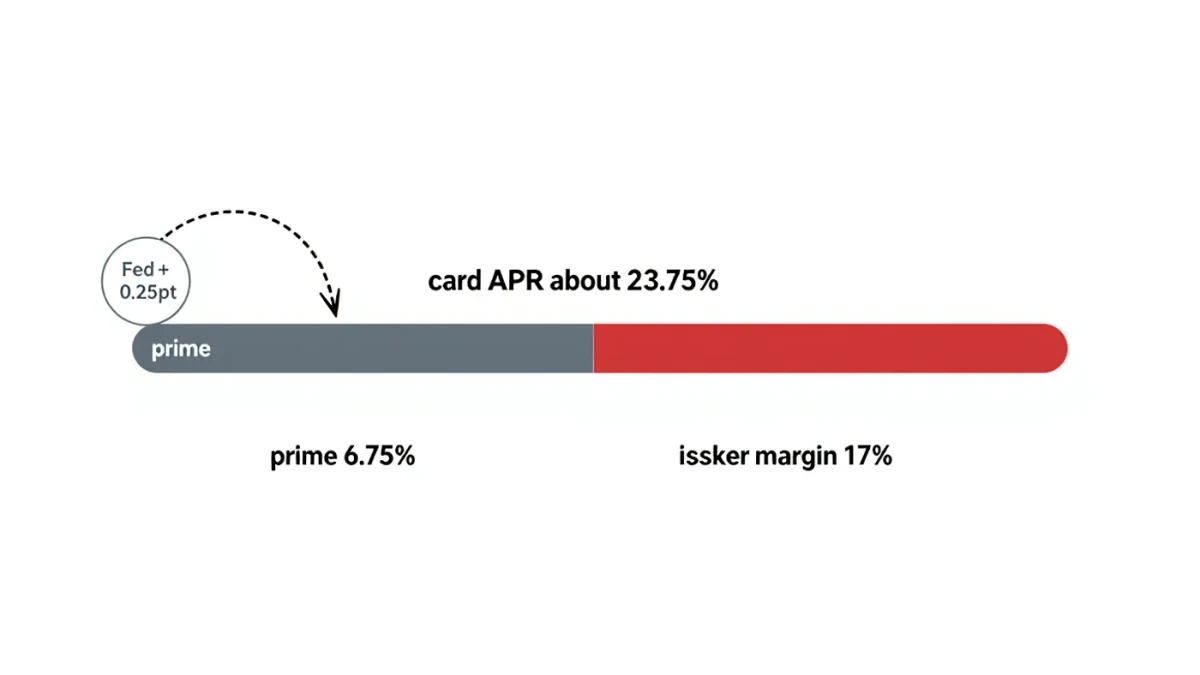
- A credit card cash advance or just using the card. Cash advances carry fees and start accruing interest immediately, so they are not cheap — but a card's annualized rate, even a high one, is typically a fraction of a payday loan's annualized cost. If you already have a card, compare before you borrow elsewhere.
- Payment plans with the biller. Utility companies, hospitals, and landlords often grant extensions or installment arrangements for free or for a small fee. This is the least expensive money you will never have to borrow. Ask before the due date.
- Employer or app-based advances. Some employers and earned-wage apps let you draw a portion of wages you have already worked. Read the fee schedule carefully: some are free, some charge a subscription or a per-draw fee, and the effective cost varies widely between them.
- Family, community, or nonprofit help. Local assistance programs and nonprofits sometimes cover exactly the kind of one-time gap that drives people to payday lenders in the first place.
What this means practically: build the comparison before the emergency, not during it. Knowing which of these you qualify for turns a two-week panic into a one-phone-call errand. If a gap in your budget keeps producing these moments, the durable fix is on the budgeting side — our budgeting guide covers building a plan that absorbs surprise expenses, and our saving section covers the emergency fund that makes the comparison unnecessary.
How do you compare two short-term offers fairly?
If you do end up comparing short-term options, compare the same three things on each one.
- The total dollars out of your pocket. Fee plus interest plus any membership or per-draw charge, added up for the full time you expect to hold the money.
- The annualized rate. Ask for the APR — the yearly cost of borrowing, including fees — in writing. If a lender will not state it, treat that as information too.
- What happens if you miss the date. The late fee, the returned-payment fee, and whether rollovers are allowed. The worst-case path is where these products differ most.
Short-term credit is not automatically a mistake. Used once, paid back on time, for a genuine one-time gap, the total cost may be modest in dollars even when the annualized rate looks alarming. The damage comes from repeat use, where fees compound against the same paycheck month after month. If you find yourself borrowing against next month to cover this one, the honest reading of the evidence is that the loan is treating a symptom, and the underlying gap needs a different fix — a spending plan, a bill negotiation, or a second income stream. Small steps count here, and the first one is just pricing the options before the deadline forces your hand.
Where the rules on payday loans come from
Short-term lending sits in a patchwork. States set the caps on loan size, fees, and renewals, and a number of states have banned the product outright. On the federal side, the Consumer Financial Protection Bureau — the agency that writes consumer rules for lenders — has issued and revised rules aimed at the ability-to-repay question and at repeated withdrawal attempts from borrower bank accounts. Because the rules move, treat anything you read about a specific fee or cap, including here, as a starting point to verify against your state's current rules and the lender's own published terms. Lenders must disclose their terms; the disclosure document is the authoritative source for what any specific loan will cost you.