An ETF — exchange-traded fund — and a mutual fund both pool many investors' money into a single diversified basket run to an index or strategy. The difference is plumbing: a mutual fund prices once a day after the market closes, while an ETF trades all day on an exchange like a stock, its price ticking with supply and demand around the value of its holdings. That single mechanical difference drives most of the practical trade-offs — cost, taxes, automation, and how your order fills.
How are they structurally different?
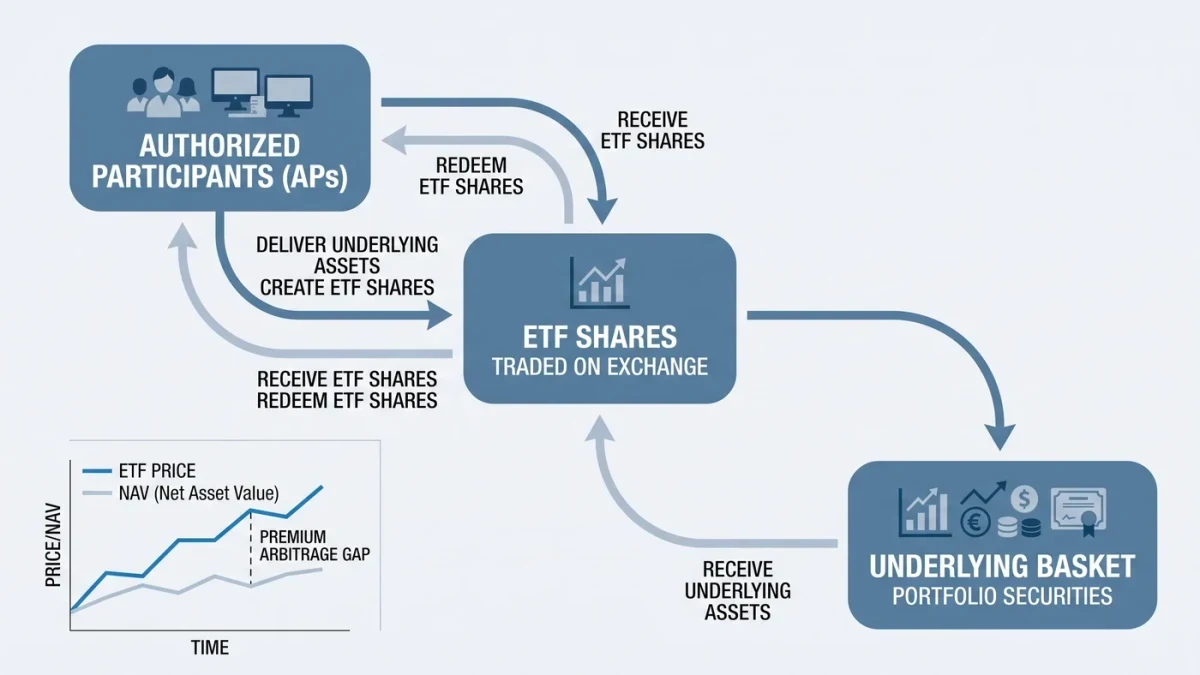
Mutual funds are bought from the fund company at the day's closing net asset value; whatever time you place the order, everyone that day gets the same price. ETFs are bought from other investors on an exchange at a live market price, which can sit a hair above or below the underlying value — the premium or discount, usually pennies on liquid funds. Neither is riskier by design; both hold identical kinds of assets underneath, and the cheapest funds of each type charge a few dollars a year per $10,000 invested.
| Feature | ETF | Mutual fund |
|---|---|---|
| When it trades | All day at market price | Once daily at closing NAV |
| Minimum investment | Price of one share, or less with fractional | Often $0–$3,000 |
| Typical index-fund fees | Among the lowest available | Equally low at the best providers |
| Automatic investing | Supported at most brokers, with quirks | The classic default, including 401(k)s |
| Taxes in taxable accounts | Usually smaller capital-gains distributions | Annual distributions can create tax bills |
| In 401(k) plans | Rare | Standard |
Fee note: compare specific funds, not averages — broad index funds of both types now charge under 0.10% at the largest providers.
Why does the tax difference matter?
In a regular taxable account, mutual funds must sell holdings when shareholders redeem, and the resulting capital gains get distributed to everyone remaining — you can owe tax on a gain you never personally booked, even in a year your fund fell. ETFs mostly avoid this through an in-kind mechanism that sheds shares without triggering sales, so their distributions are typically smaller. Inside an IRA or 401(k) the point evaporates — tax-sheltered accounts make both wrappers equal on taxes, which is why the 401(k) menu's mutual funds cost you nothing.
Which one should a beginner choose?
Match the wrapper to the account. In a workplace 401(k), you will use mutual funds — or their collective investment trust cousins — because that is what the menu offers. In an IRA at a brokerage, either works; the broadest, cheapest fund you will actually automate is the right answer. In a taxable brokerage account, the ETF's tax edge and all-day trading argue in its favor, provided your broker supports fractional shares — otherwise one share of a $500 fund forces lumpy purchases, and the mutual fund's exact-dollar investing keeps a monthly rhythm intact.
Where do people go wrong?
Three habits corrode returns. Trading ETFs just because they trade — intraday pricing is a convenience, not an invitation, and the buy-and-hold math beats the in-and-out math across decades. Chasing exotic ETFs — leveraged, inverse, single-theme — that use the same wrapper to package entirely different risk. And reflexively avoiding mutual funds in retirement accounts where the tax argument does not apply, paying needless attention to a difference that does not exist there.
FAQ
Are ETFs riskier than mutual funds?
No — risk lives in what the fund holds, not the wrapper. An ETF and a mutual fund tracking the same index have nearly identical ups and downs; the differences are trading mechanics, costs, and tax handling.
Can I convert a mutual fund to an ETF?
Some providers offer in-kind conversions within their own fund families without triggering capital gains; otherwise selling a mutual fund in a taxable account may realize gains. Check the provider's conversion program before selling anything.
Which is better for automatic monthly investing?
Mutual funds were built for it — dollar amounts buy exact fractions at the closing price. Most large brokers now automate ETF purchases too, and fractional shares close the gap; choose the fund you will stick with and let the automation question follow.